
March 27, 2026
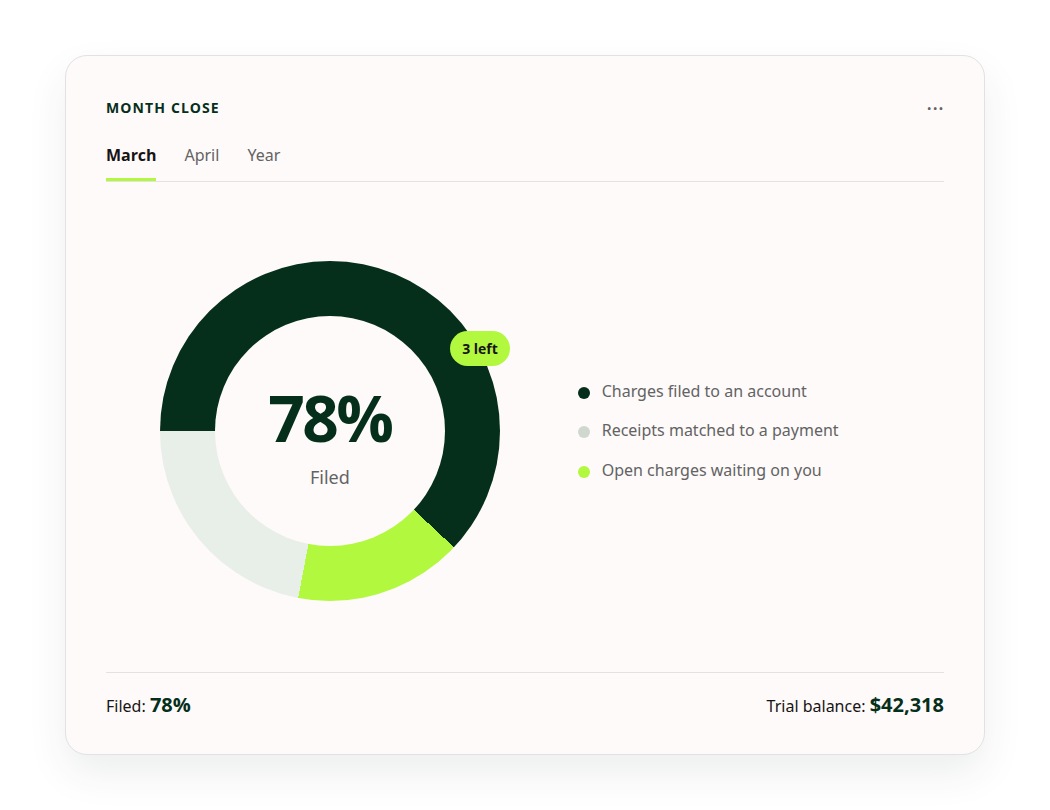
You moved $2,100 from checking into a holding spot for payroll tax. In Pruvon, that line files to Tax set aside. It is cash you are holding. It is not a filed return, and it is not the contractor payment. Pruvon does not file tax returns and is not a CPA firm.
Payroll tax that sits before you file is cash you hold back, not a return you already sent. When wages leave the account, a portion often stays earmarked for amounts that will move later. In Pruvon you see that as bank data—money that has not left yet, or money that left under a different label when it finally remits. The set-aside is a holding pattern. It is not the filing itself.
Keep that distinction sharp. A contractor payment is pay for work. Payroll tax set aside is cash reserved so the wage-related remittance does not surprise the account later. Mixing those lines makes the bank view harder to read. Pruvon is built for viewing what moved and what is held—not for preparing returns, and not as a CPA firm. Nothing here is tax or legal advice.
What “set aside” means in the bank view
Payroll tax set aside is cash held back. It is not a filed return. Treat it as reserved money until the remittance actually leaves the account.
Set-aside cash is still in the account until remittance posts.
Do not spend reserved payroll tax as if it were free cash.
The hold is a label in your view, not a filed return.
A transfer or balance held for wage-related remittance still sits in your view as cash you should not spend twice.
When the remittance posts, the bank line shows money leaving—that is the filing movement, not the set-aside itself.
Contractor payouts stay in their own lane; they are not payroll tax held back from wages.
Keep contractor pay separate
Contractor invoices are for work delivered. They post as payments out, not as wage tax held in reserve. If you fold contractor pay into a payroll-tax set-aside label, the bank story breaks. You lose the ability to see who got paid and what cash is still reserved for remittance. File contractor lines against contractor pay. Leave payroll tax set aside for the wage-related hold only. Short labels and matching receipts keep later review simple.
Mark the set-aside when wages post so available cash stays honest.
When remittance clears, close the hold against that bank line.
Never file a contractor invoice into the payroll-tax hold.
When wages post, note any amount you are holding for later remittance—and do not treat that hold as already filed.
When the remittance leaves the account, file that bank line as the remittance movement, not as new contractor spend.
Keep contractor payouts on their own lines so reserved payroll tax cash never looks like invoice pay.
How Pruvon keeps the hold visible
Pruvon shows bank data you already have. Label the set-aside clearly so available cash is not overstated. When remittance posts, match it and close the hold in your view. That habit keeps payroll tax sitting in the right mental bucket until it actually leaves. It also keeps contractor pay readable on its own. Use the same short sentences every pay cycle: hold, remittance, contractor—three different stories. This guide is for viewing cash, not for filing returns. Pruvon is not a CPA firm, and this is not tax or legal advice.